01
Identity and membership
- Insurance e-card or policy card
- Policy number and member ID
- Government photo ID
- Employee ID for a corporate policy
- Patient and proposer contact details
JEWCC helps eligible patients prepare and submit cashless documentation for planned treatment. We explain the process and coordinate records; the insurer, TPA or government scheme makes the final authorisation decision.
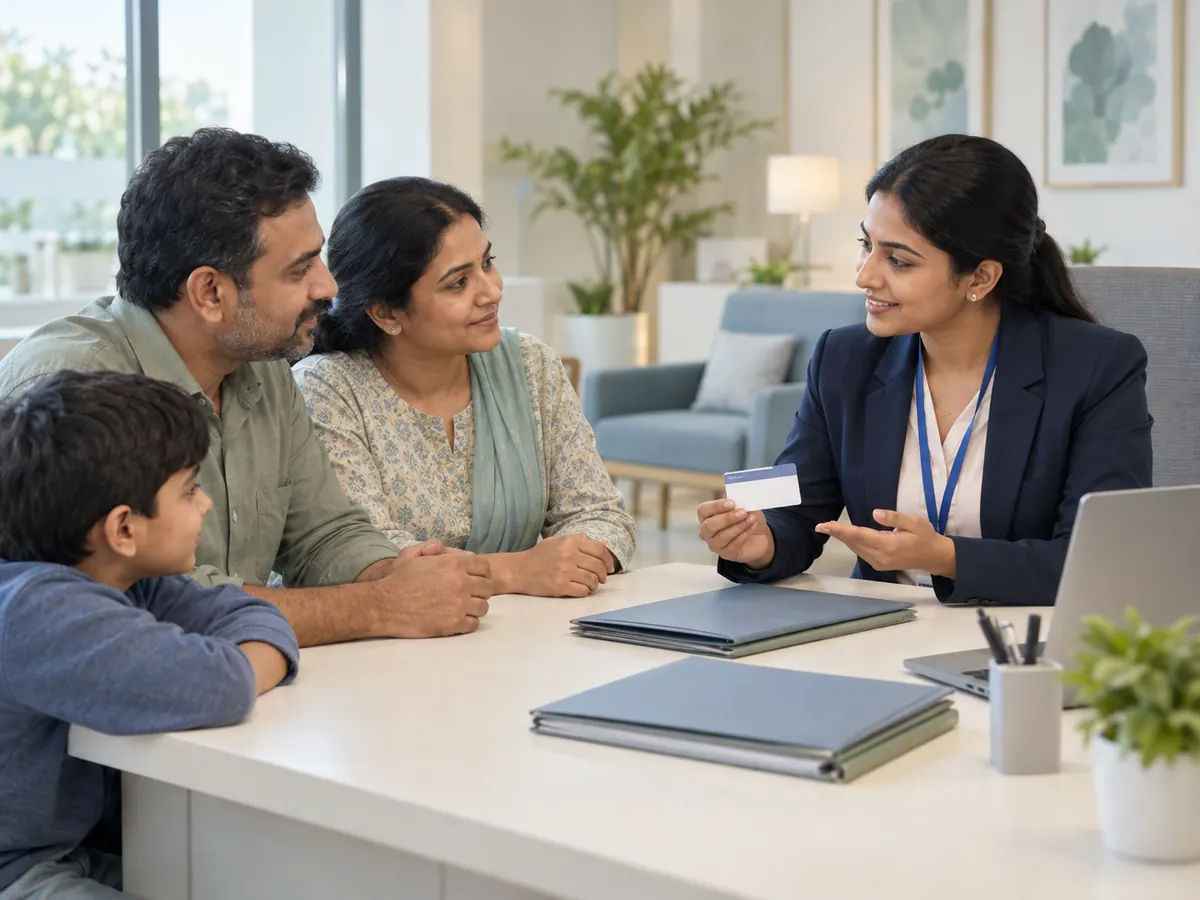
For a planned procedure, start early. A complete request is easier to process, while an insurer query, policy mismatch or missing investigation can delay a decision.
Send the policy card, member ID and proposed treatment details before the planned procedure. The team checks the insurer, TPA and applicable centre.
The doctor confirms the diagnosis, medical need and treatment plan. An estimate can then be prepared for pre-authorisation.
The hospital or centre submits the request and supporting records. The insurer or TPA may approve, query, modify or decline it.
If approved, treatment proceeds within the authorisation conditions. A revision may be requested if the clinical plan or cost changes.
At discharge, the final bill and clinical documents are submitted. The patient settles non-payable items, co-pay, deductible or any amount outside approval.
For a complete cashless request, insurers are expected to decide pre-authorisation immediately and within one hour, and final discharge authorisation within three hours of receiving the hospital request. Missing information, queries or policy issues can still affect the actual journey.
Read the IRDAI health-insurance guidanceThe exact checklist varies by policy and procedure. The treating team prepares the clinical plan and estimate; the patient or attendant should ensure membership and identity details match the policy.
Final bill and break-up, discharge summary or procedure notes, prescriptions, investigation reports, pharmacy bills and—where relevant—implant or intraocular-lens sticker and invoice. Keep a copy of the approval and every document submitted.
The insurer can approve less than the estimate or apply policy conditions. Ask for the approved amount and exclusions before treatment whenever possible.
Names are separated by role: an insurer issues or underwrites the policy; a TPA may administer its health claims. Company names and panels change, so call with the exact name printed on your current card.
Current names are used, with familiar former names where helpful.
The TPA shown on your e-card may handle the authorisation.
Please confirm before treatment: inclusion in this directory does not guarantee cashless approval for every policy, branch, procedure or date. Network status, product conditions and authorisation must be checked for the individual patient.
CGHS supports eligible serving and retired Central Government beneficiaries and dependants. The route can differ according to beneficiary category, referral, whether the procedure is listed, and the facility where care is delivered.
Contact JEWCC before the planned visit with the CGHS card and referral or prescription. We can check what is needed for the proposed eye-care service; final eligibility remains subject to prevailing CGHS rules and the applicable empanelment.
JEWCC is working toward additional institutional and government-linked pathways, including GIPSA/PPN and ESIC-related processes. Details will be published only after empanelment, eligible locations and documentation requirements are confirmed.
Until then, these should not be assumed to be active cashless panels. Please call for the latest status.No. Cashless means the approved admissible amount is settled directly by the insurer or TPA. Co-pay, deductible, non-medical items, package or sub-limit differences, upgrades and any amount outside the final authorisation remain payable by the patient.
Coverage depends on medical necessity and the exact policy. Waiting periods, exclusions, cataract or procedure sub-limits, room-category rules and lens limits may apply. The insurer or TPA—not the hospital—makes the final coverage decision.
Contact JEWCC as soon as surgery is advised and preferably several working days before the planned date. Queries or additional-document requests can extend the process even though complete cashless requests have regulatory turnaround expectations.
A declined cashless request does not always mean the medical treatment itself is unnecessary. Ask for the reason. Depending on the policy and clinical urgency, options may include responding with more records, self-payment followed by reimbursement, changing the date or discussing another treatment plan.
A policyholder may choose a primary indemnity policy. If its available cover is insufficient, the primary insurer can coordinate with another insurer subject to both policies and the applicable process. Share all active policy details early.
No. The required referral or prescription, beneficiary category, listed procedure, empanelled facility and prevailing CGHS rules must all be checked. Serving employees and pensioners may follow different payment or permission pathways.